Every European traveller knows the small sting. You land in Lisbon or Kraków, tap your card for a coffee, and weeks later your bank statement reveals that the coffee cost rather more than the menu said. The exchange rate was poor, the fee was tucked away, and nobody apologised.
In 2015, Nik Storonsky and Vlad Yatsenko started Revolut in London with a pitch so modest it barely sounded like a company: a card that let you spend abroad without losing money on the exchange rate. Eleven years later, the card has grown a bank.
Revolut ended 2025 with 68.3 million retail customers, $6.0 billion in revenue and $2.3 billion in profit before tax, according to its annual results. Revenue rose 46 per cent in a year. Customers kept $67.5 billion with the company, up two-thirds. Those are the company’s own figures, but they describe a business that has long outgrown the label start-up.
Investors have noticed. In July, an employee share sale valued Revolut at $115 billion, as the Wall Street Journal first reported and CoinDesk’s Francisco Rodrigues summarised. That compares with $75 billion in November 2025 and $45 billion in 2024. The company’s paper value rose by about 50 per cent in less than a year.
One feature at a time
The early idea was simple, and the strategy that followed was even simpler: keep adding things. Business accounts, share trading, savings and loans arrived one feature at a time, each easy to try inside the same app. Revolut now counts 767,000 business customers alongside its retail users, and its lending book reached $2.9 billion last year, more than double the year before, its results say.
The company is not shy about where this is meant to go. It is aiming for 100 million customers by mid-2027 and says it will invest $13 billion over the next five years.
Via Vilnius
Much of this was built from Lithuania. Revolut’s European bank is registered there and supervised by the Bank of Lithuania, LRT reported. Under EU rules, a bank licensed in one member state can serve customers across the single market. A licence from a country of under three million people became, in effect, a passport to 450 million.
That European base keeps growing. In May 2025 Revolut chose Paris for its Western European headquarters, pledged more than €1 billion of investment in France over three years and applied for a French banking licence, John Reynolds reported for Tech.eu. It already had more than five million French customers. Revolut says it now holds a banking licence in more than 30 of its 40 markets.
Growing pains
Growth this fast leaves marks, and Revolut has a few. In March 2023 its auditor, BDO, said it could not verify £477 million of the company’s £636 million revenue for 2021, pointing to IT systems that did not allow its controls to be tested properly, UKTN’s Oscar Hornstein reported. In April 2025 the Bank of Lithuania fined Revolut Bank €3.5 million for weaknesses in monitoring transactions. The central bank found no confirmed cases of money laundering, and Revolut agreed a plan to fix the gaps, according to LRT.
At home, patience was required too. Revolut applied for a British banking licence in 2021 and entered a supervised “mobilisation” phase in July 2024, Payment Expert reported. Only on 11 March 2026 did the Prudential Regulation Authority lift the restrictions, letting Revolut operate as a full bank for its 13 million British customers, the company said. Storonsky called the UK bank “a long-term strategic priority”, which, after a wait of more than four years, is one way of putting it.
America, not London
The obvious next chapter is a listing. Storonsky told Bloomberg in April that an IPO is about two years away and most likely in the United States, The Next Web’s Ana-Maria Stanciuc reported. The Financial Times reported that investors are discussing a market value of $150 billion to $200 billion, according to TechCrunch. Revolut declined to comment on that report.
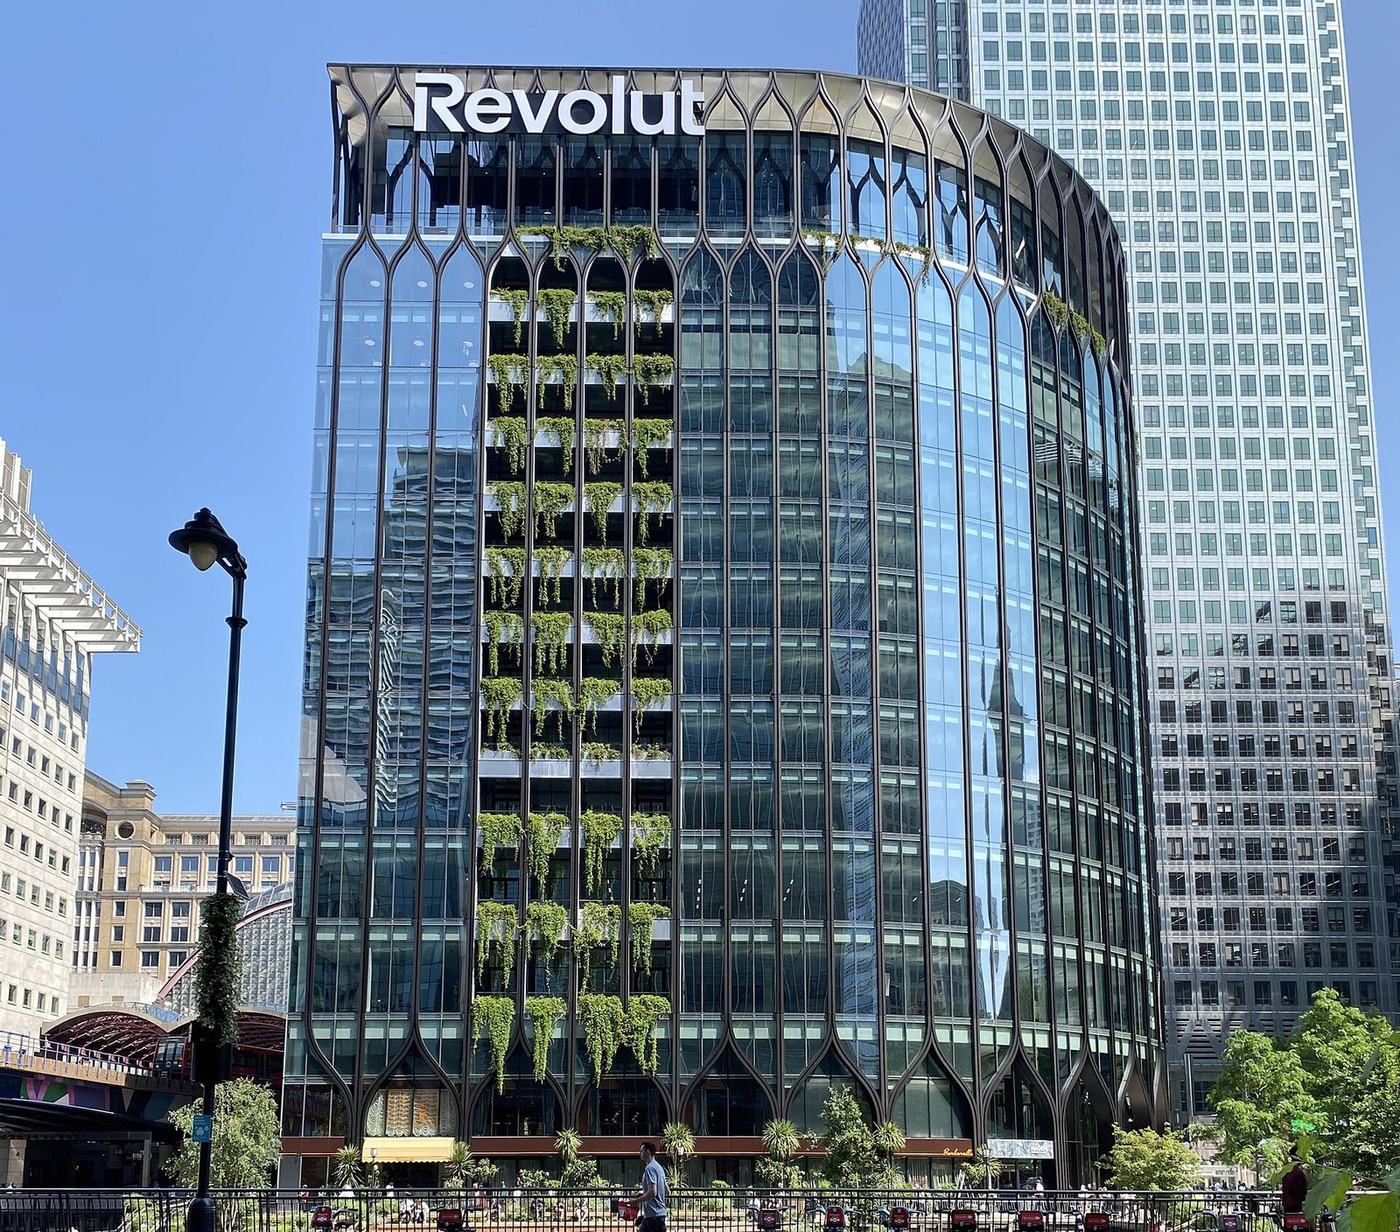
For Britain, which has courted the company, this is a sore point. Chancellor Rachel Reeves opened Revolut’s Canary Wharf headquarters, The Next Web noted. For the rest of Europe, the more interesting question is whether a company built on an EU licence, with hubs in Vilnius and Paris, ends up priced and traded on the other side of the Atlantic. Revolut filed for a US national bank charter in March, so the American ambitions are not just about shares.
Still to prove
The profits show that a European app can make serious money from everyday banking. The deposits show that tens of millions of people trust it with their wages. The valuation shows enthusiasm, but it comes from a private share sale, not from a market where anyone can sell.
Two things are still unclear: whether its controls keep pace as Revolut pushes into dozens more countries, and whether Europe can keep the next company of this size listed at home. For millions of travellers, the coffee in Lisbon now costs roughly what the menu says. Whether Revolut can make banking itself that simple, at this scale and without the stumbles, is a question for the next ten years.